The Hidden Cost of Paying Off Debt Too Fast
You have credit card debt that's barely shrinking. You know your retirement contributions could help you pay it off faster. So, should you stop saving for retirement?
I understand why that might seem like a good idea, especially when interest charges keep eating into your monthly payments.
On a recent episode of Becoming Financially Confident, Juliet and I discussed a listener's situation that I think many people can relate to.
Our listener has $9,600 in credit card debt at 24% APR. They're currently contributing 6% of their pay to a 401(k), and their employer matches contributions dollar for dollar up to 4%.
Now they're considering pausing their retirement contributions for an entire year to focus on paying off the debt.
But is that really the smartest move?
Why Stopping Your 401(k) May Cost You
The first thing I looked at was the employer match.
When your employer offers a dollar-for-dollar match up to 4% of your pay, you're generally receiving an additional dollar from your employer for every dollar you contribute within that limit, subject to the plan's rules.
That's valuable money you could be leaving on the table.
If you stop contributing entirely, you could miss out on future employer matching contributions.
That's why my general recommendation is to keep contributing enough to receive your full available employer match rather than stopping your retirement savings altogether.
Of course, every financial situation is different, and employer matching contributions may be subject to vesting requirements.
What About the 24% Credit Card Interest?
Now, let's talk about the credit card debt.
At 24% APR, a $9,600 balance is expensive to carry.
To put that into perspective, if we multiply $9,600 by 24%, we're looking at $2,304 in annualized simple interest, assuming the balance stays unchanged.
That's a significant amount of money.
Your actual interest charges will depend on your daily balance, payments, and credit card terms.
So, I'm certainly not suggesting that you ignore your credit card debt while continuing to save for retirement.
What I'm saying is that we need to find a way to address both financial priorities.
And in this listener's situation, I think there's a reasonable place to start.
Could Reducing Your Contributions Be a Better Option?
Here's something important I noticed.
Our listener is currently contributing 6% of their pay to their 401(k), but their employer only matches contributions up to 4%.
That gives us an option worth considering.
Instead of stopping retirement contributions entirely, what if they reduced their contribution from 6% to 4%?
They could potentially continue receiving the full available employer match while directing some additional take-home pay toward their credit card debt.
Now, keep in mind that the extra money in their paycheck won't necessarily equal 2% of gross pay. Taxes and the type of retirement contribution can affect how much they actually take home.
They'll also need to review their employer's specific plan rules.
Will this strategy eliminate $9,600 in debt overnight?
Of course not.
But it may help them make progress on their debt without completely putting retirement savings on hold.
And that's what I want you to understand.
You don't always have to choose one financial goal at the expense of another.
Sometimes, the better approach is finding a balance.
Don't Forget Why the Debt Happened
Juliet brought up another excellent point during our conversation.
Before we start building a repayment plan, we need to understand how the credit card debt accumulated in the first place.
Was it an unexpected emergency?
Did you experience a period of reduced income?
Or have you developed spending habits that regularly push your expenses beyond what you earn?
I think this is an important conversation because paying off your credit card is only part of the solution.
If we don't address what caused the debt, there's a chance we'll find ourselves right back in the same situation.
That's why I often talk about having a plan.
We've discussed strategies like the debt snowball and debt avalanche on the show.
With the snowball method, you focus on paying off your smallest balances first to build momentum.
With the avalanche method, you prioritize debts with the highest interest rates to reduce interest costs.
Neither approach works unless you're willing to follow through.
My advice is to choose a method that fits your financial situation and stick with it.
When Might Stopping Contributions Make Sense?
Now, I want to be clear about something.
I'm not saying that you should never stop or reduce your retirement contributions.
There are situations where that decision deserves a closer look.
Maybe you're facing a financial emergency.
Maybe you're struggling to cover essential expenses.
Or perhaps your employer's retirement plan works differently from the one in our listener's example.
Your income tax situation can also affect the calculation.
That's why I believe it's important to look at your entire financial picture before making a decision.
Here are a few things I'd encourage you to review:
-
Your employer's retirement plan: How much do you need to contribute to receive the full match, and what are the vesting rules?
-
Your credit card debt: How much do you owe, and what interest rates are you paying?
-
Your monthly budget: How much can you realistically afford to put toward debt?
-
Your emergency savings: Do you have money set aside for unexpected expenses?
-
Your tax situation: How might changing your retirement contributions affect your take-home pay and taxes?
The goal isn't to make a quick decision because you're frustrated with your debt.
It's to understand your options and make a decision that supports your long-term financial health.
Other Important Lessons From This Episode
Juliet and I also covered several other financial situations that reminded me how important it is to plan ahead.
How Having a Baby Changes a Couple's Finances
We discussed a married couple who had always kept their finances separate and split their expenses equally.
Everything worked until they had a baby.
When one partner decides to stay home to raise a child, the financial arrangement can become more complicated.
I shared some mistakes from my own marriage and why I've learned that the person bringing home the paycheck isn't necessarily contributing more to the household.
We also talked about retirement planning, life insurance, financial independence, and recognizing the value of unpaid childcare.
Retirement Savings Regrets
We looked at why delaying retirement savings has become such a significant financial regret for many Americans.
And here's what I want you to remember.
You don't have to wait until you can afford to invest hundreds of dollars every month.
If you can start with a manageable amount, start there.
The important thing is to build the habit and make adjustments as your financial situation improves.
Student Loan Delinquencies
Another topic that caught my attention was how borrowers with relatively small student loan balances are struggling to keep up with payments.
You might assume that owing less money automatically makes repayment easier.
But that's not necessarily the case.
If you're falling behind on your student loans, I'd encourage you to contact your loan servicer and ask about the repayment options available for your specific loan.
Ignoring the problem generally won't make it go away.
AI Voice-Cloning Scams
This one really concerns me.
Scammers can now use artificial intelligence to imitate the voice of someone you love.
Imagine getting a phone call that sounds exactly like your child or grandchild, telling you they're in trouble and desperately need money.
Would you know whether the call was real?
That's why I recommend establishing a private family codeword.
It's a simple way to add another layer of protection.
I'd also encourage you to follow the Federal Trade Commission's advice: contact your loved one directly using a trusted phone number before sending money.
Don't rely on a familiar-sounding voice alone.
When a Cosigned Car Loan Goes Unpaid
We also answered a question from a parent who cosigned a car loan for their son.
Now the son has missed payments, and the parent is worried about their credit.
Here's something I always remind people.
When you cosign a loan, you're taking on real financial responsibility.
If the primary borrower stops paying, the lender may hold you responsible for the debt.
And even if the vehicle is voluntarily surrendered or repossessed, you may still owe money after it's sold.
That's why I encourage people to think carefully before cosigning and to contact the lender as soon as repayment problems arise.
The Bottom Line
If you're carrying high-interest credit card debt, I understand why you'd want to throw every available dollar toward paying it off.
Nobody enjoys watching interest charges pile up month after month.
But before you stop contributing to your 401(k), I want you to consider what you might be giving up.
Your employer match could be a valuable part of your retirement savings.
And if you're contributing more than your employer matches, there may be an opportunity to adjust your contributions while directing more money toward your debt.
At the same time, we can't ignore the importance of having a realistic repayment plan.
Here's one money move I want you to make today.
Pull out your latest pay stub and review your employer's retirement plan.
Find out exactly how much you need to contribute to receive your full available match.
Then take a look at your monthly budget and see whether there's room to direct more money toward your highest-interest debt.
You don't have to solve everything today.
You just need to take the next step toward a plan that works for you.
And remember, it's going to be okay.
Have a money question you're struggling with?
Juliet and I would love to hear from you.
Send Your Money Question to Becoming Financially Confident
Ralph Estep Jr. is a licensed public accountant and financial counselor. This article provides general financial education and is not individualized financial, tax, investment, or legal advice.
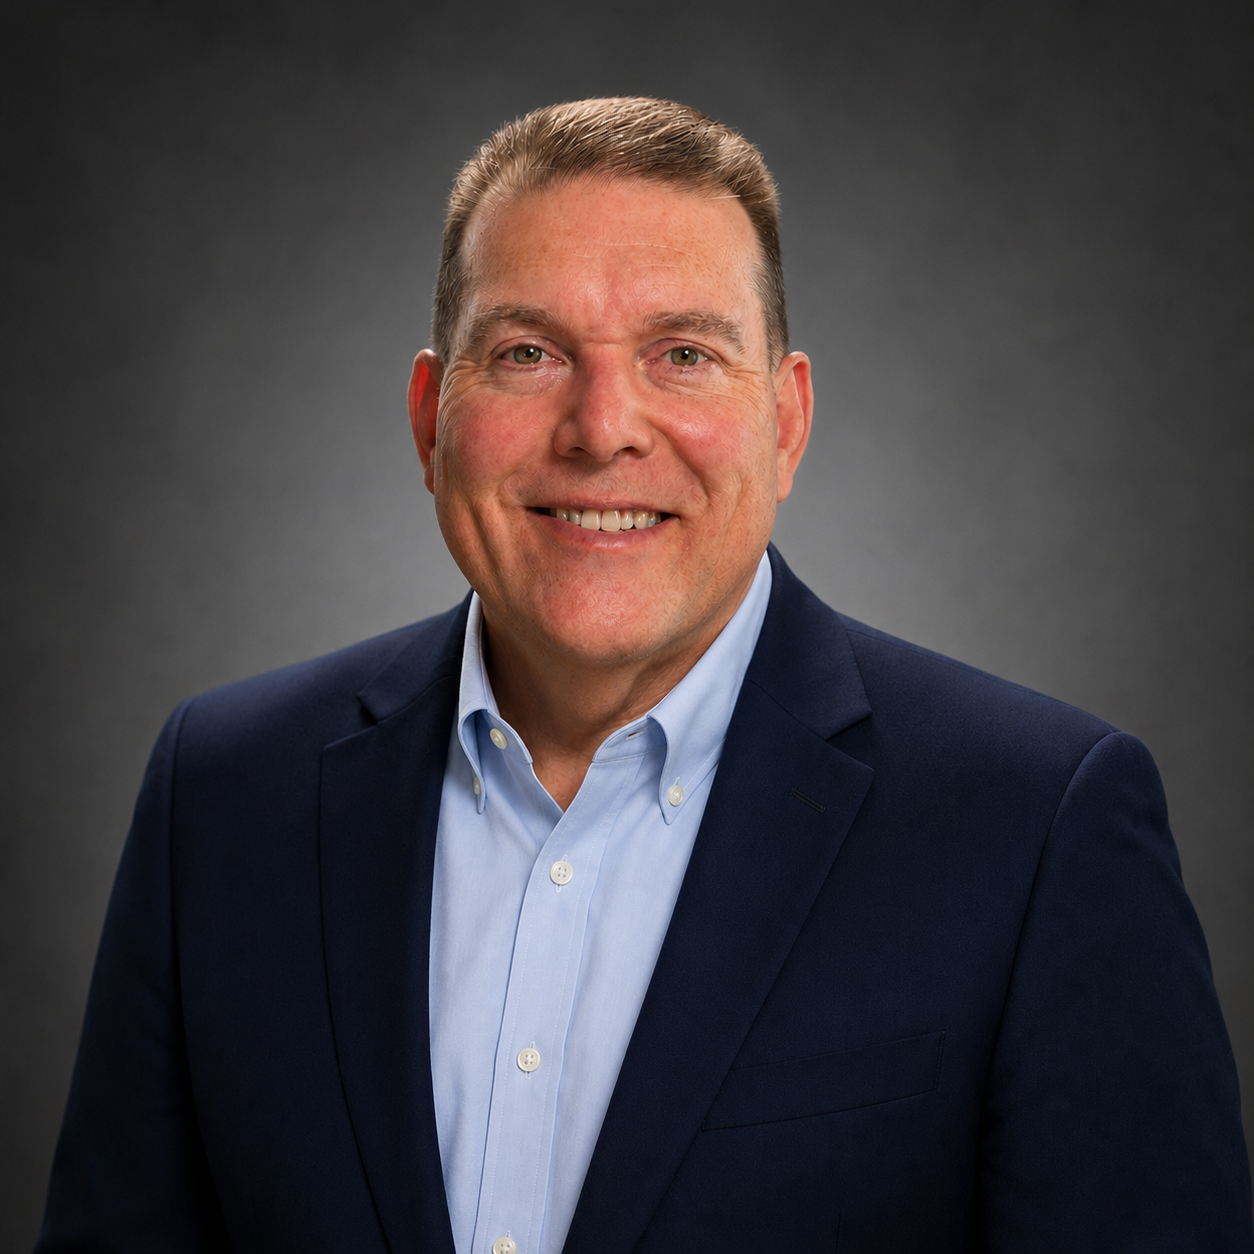
Licensed Public Accountant
Ralph V. Estep, Jr. is a Delaware-based Licensed Public Accountant (LPA), author, rancher, and media host with more than 30 years of experience in finance, taxation, and small-business leadership. As the founder of Saggio Accounting+PLUS and the creator of the Ask Ralph Media network, Ralph helps entrepreneurs, creators, and everyday families replace money confusion with clarity, confidence, and practical next steps — without shame and without hype.
Ralph's work blends deep professional expertise with a coach's mindset and a communicator's heart. He has held leadership roles across public accounting, financial institutions, law firms, and technology organizations, bringing a rare combination of traditional accounting rigor and modern systems thinking to the people he serves. A graduate of the University of Delaware and Wilmington University (MBA), he is known for turning complex money topics into simple, repeatable frameworks that help people make wiser decisions and build lasting financial stability.
He is the host of Becoming Financially Confident, a live weekday show built on a single conviction: most money stress is not a character problem but a systems problem, and shame is what keeps people from fixing it. The show grew out of Financially Confident Christian, which Ralph hosted for more than 1,200 episodes across eight seasons and earned national recognition. The new show offers the same host and the same feed, opened up to a wider audience.
Through Ask Ralph Media, Ralph hosts several other programs. Grit and Growth Business… Read More
Financial Infidelity: How Hidden Debt Can Break Trust in a Marriage