What Is Credit Utilization and Why Does It Matter?
If you have a credit card, there’s a number on your statement that deserves more attention than it probably gets.
It’s called credit utilization.
Credit utilization is the percentage of your available revolving credit that you’re currently using. It’s one of the factors discussed when looking at your FICO credit score, and understanding how it works can help you make more informed decisions about your credit cards.
The good news? You don't need to carry a balance or pay interest just to build credit.
Let's break down what credit utilization means, how to calculate it, and what you can do to keep it under control.
What Is Credit Utilization?
Credit utilization is the percentage of your available revolving credit that you're using.
Here's a simple example.
Let's say your credit card has a $3,000 credit limit and your current balance is $900.
The calculation looks like this:
$900 ÷ $3,000 = 30% utilization
So your credit utilization is 30%.
The important thing to understand is that utilization looks at how much of your available credit you're using compared with how much credit is available to you.
Why Does Credit Utilization Matter?
Credit utilization is one of the numbers that can affect your credit score.
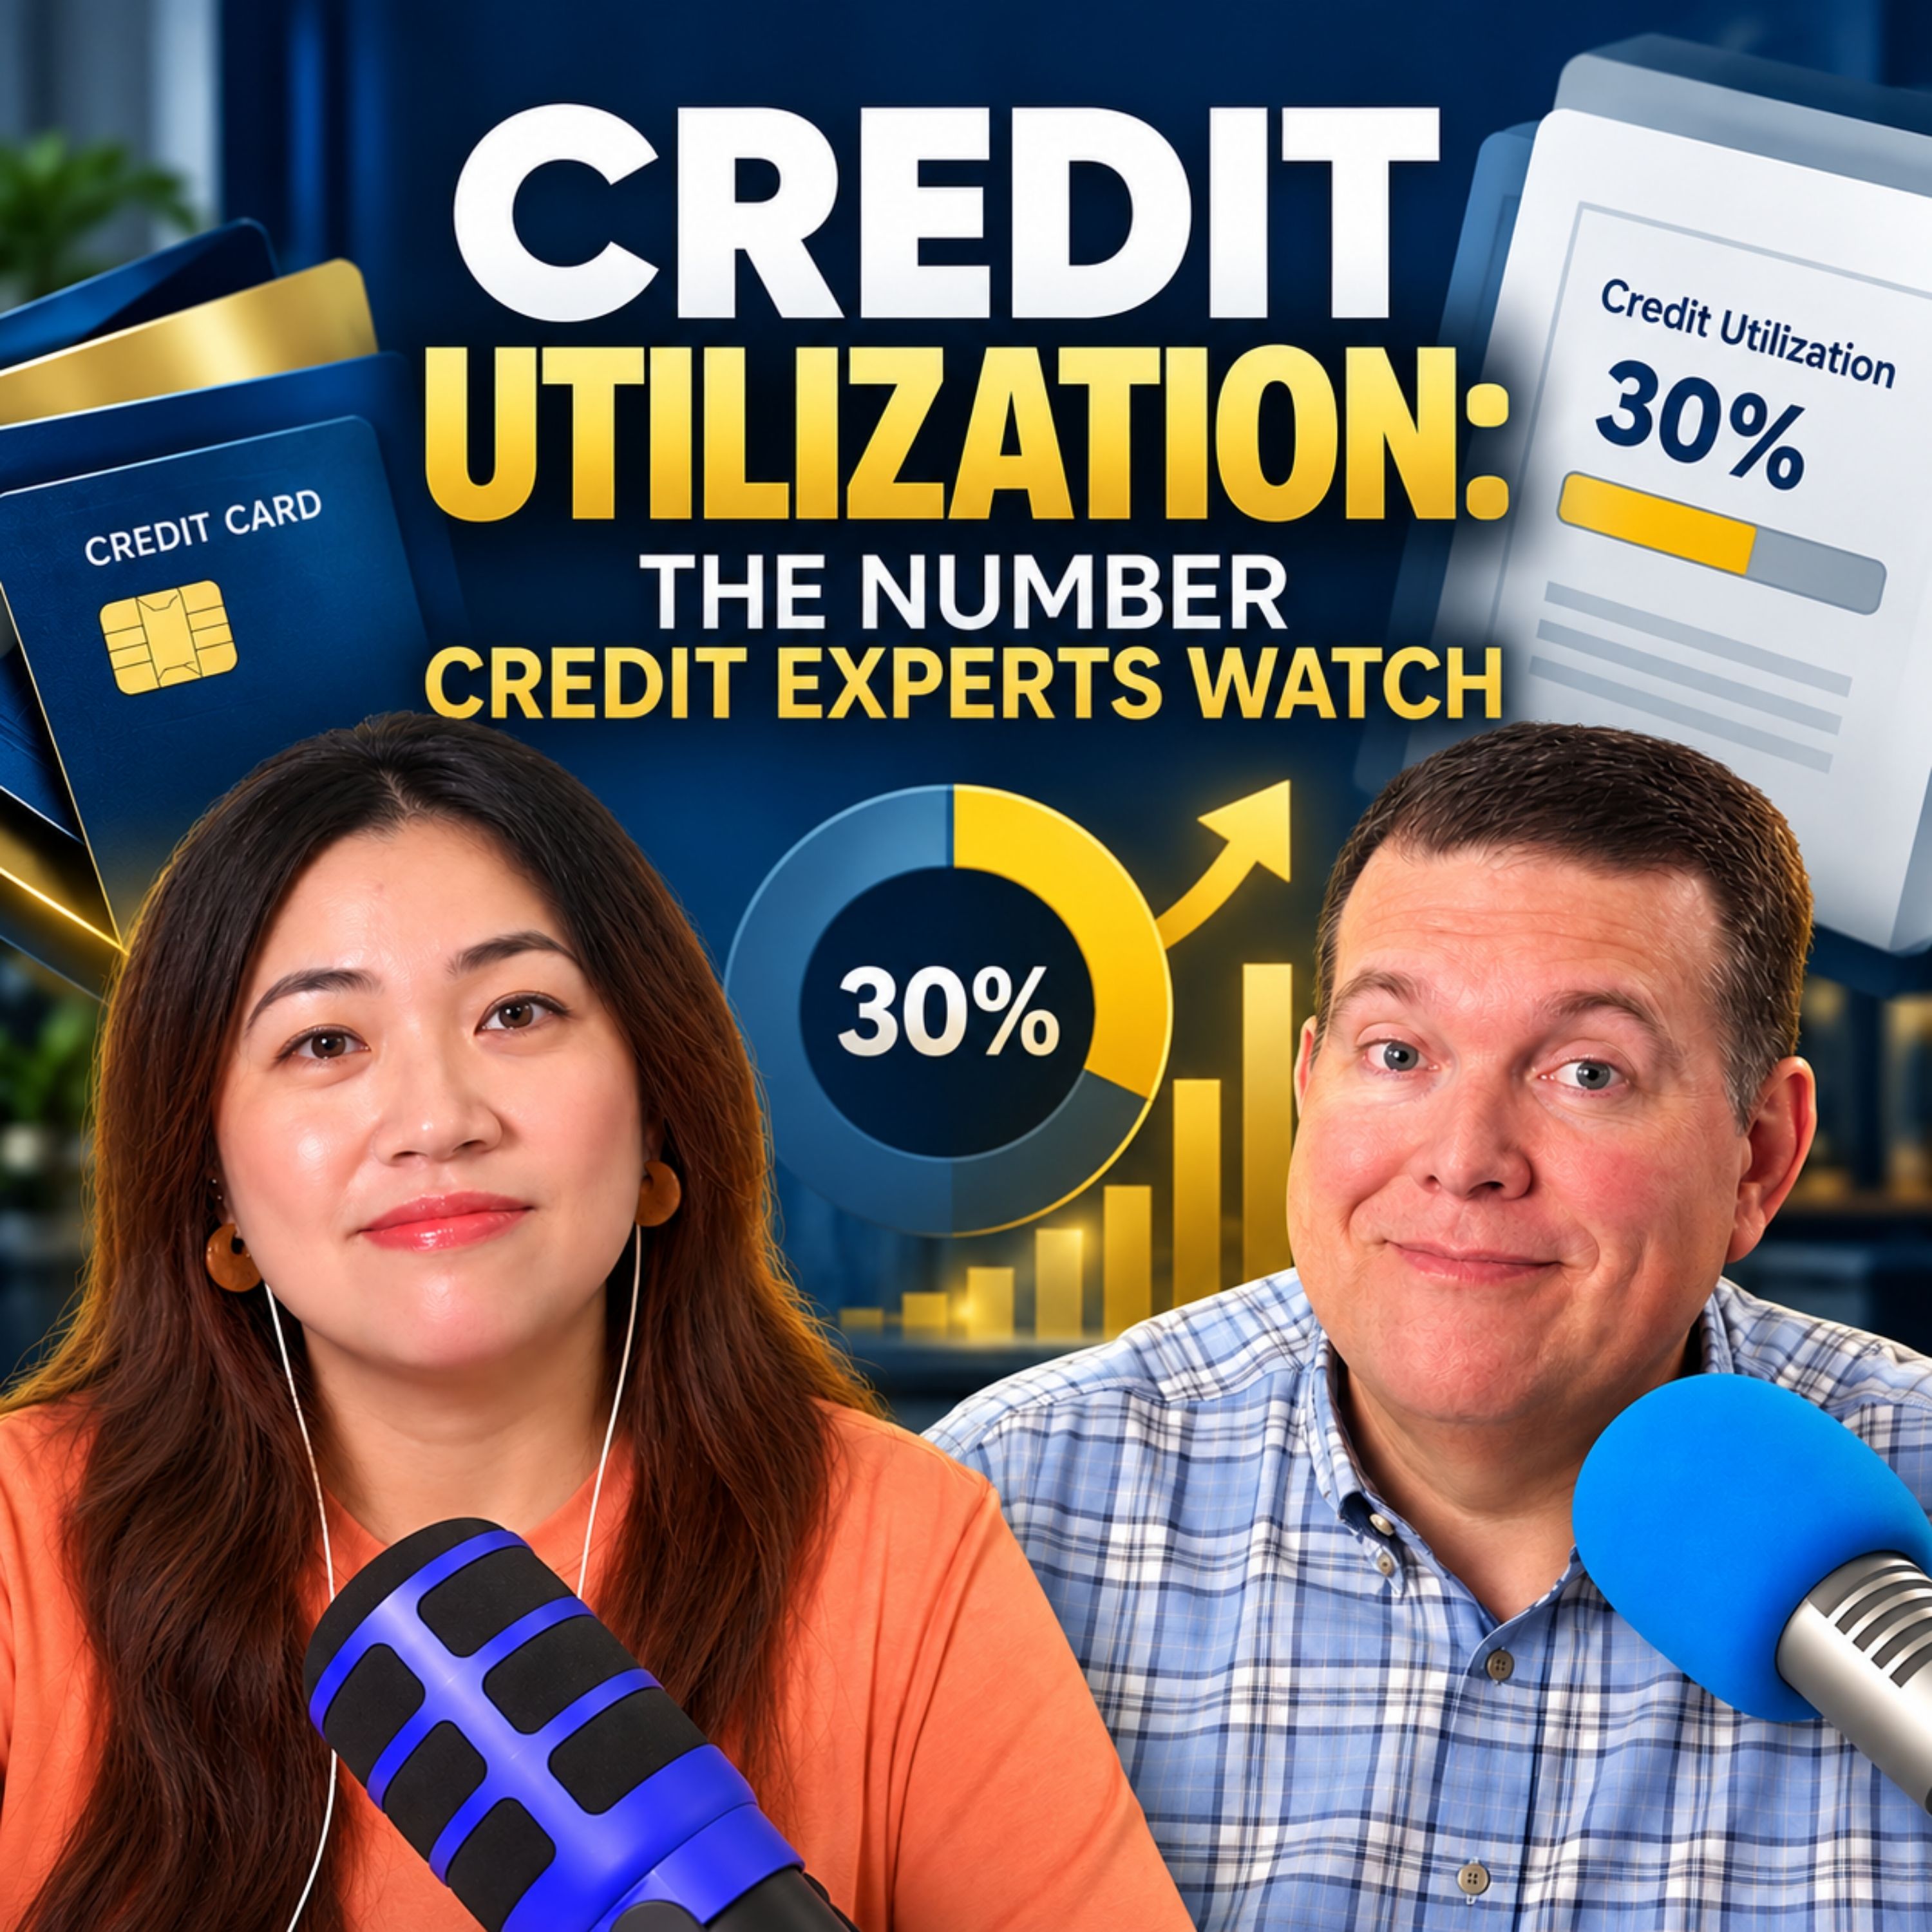
The episode discusses how amounts owed make up 30% of a FICO score, which is why your revolving credit balances deserve attention.
A high balance relative to your available credit can result in a higher utilization ratio.
That's why it's worth knowing both numbers:
-
How much credit you have available
-
How much of that credit you're using
Once you know those numbers, you can see where your utilization stands.
What Credit Utilization Should You Aim For?
The episode discusses keeping credit utilization below 30%, with 1% to 9% presented as the target range.
That doesn't mean you need to carry a balance from month to month.
In fact, you don't need to pay interest on a credit card balance just to build credit.
The goal is to understand how your balances compare with your available credit and manage your cards accordingly.
How Do You Calculate Credit Utilization?
The calculation is simple:
Credit card balance ÷ credit limit × 100 = credit utilization
For example:
$900 ÷ $3,000 × 100 = 30%
If you have multiple revolving credit accounts, you can also look at your overall utilization by comparing your total balances with your total available credit.
For example, if you have:
-
Card 1: $900 balance / $3,000 limit
-
Card 2: $500 balance / $5,000 limit
Your total balances are $1,400.
Your total available credit is $8,000.
That gives you:
$1,400 ÷ $8,000 = 17.5% utilization
Looking at the bigger picture can give you a clearer idea of how much of your available revolving credit you're using.
How Can You Lower Your Credit Utilization?
If your credit utilization is higher than you'd like, there are several ways you may be able to bring it down.
1. Make Payments Before Your Statement Closes
One option discussed in the episode is making payments during the billing cycle and before the statement closes.
Why does that matter?
Your balance can change throughout the month. Paying down some of the balance before the statement closes can help reduce the amount that's reported.
2. Ask for a Higher Credit Limit
Another option is asking your credit card issuer for a higher credit limit while keeping your spending habits the same.
For example, imagine you have:
$900 balance ÷ $3,000 limit = 30% utilization
If your available credit increased to $6,000 while your balance stayed at $900:
$900 ÷ $6,000 = 15% utilization
The balance didn't change.
The available credit did.
That can change the utilization calculation.
Of course, a higher credit limit shouldn't become an excuse to spend more than you can afford.
3. Spread Spending Across Cards
If you have multiple credit cards, spreading your spending across cards can help prevent one card from carrying a disproportionately high balance.
The key is still to keep your overall spending manageable.
Having multiple cards doesn't mean you should spend more. It simply gives you more available revolving credit to work with.
Should You Carry a Balance to Build Credit?
No.
You don't need to carry a credit card balance and pay interest just to build credit.
This is an important distinction.
Using a credit card responsibly and managing your balances is different from intentionally carrying debt because you think you need to pay interest to establish credit.
If you're using a credit card, pay attention to your balances, your available credit, and when your statements close.
What Happens When You Close a Credit Card?
Closing a paid-off credit card can affect your overall available credit.
Here's why.
Imagine you have two cards:
-
Card 1: $3,000 credit limit
-
Card 2: $5,000 credit limit
That's $8,000 in total available credit.
If you pay off Card 2 and close it, your available credit drops to $3,000.
If you still have a balance on Card 1, that same balance now represents a larger percentage of your available credit.
That's why closing a paid-off card can increase your overall utilization ratio.
Before closing a card, understand how doing so could change your available credit.
Credit Utilization: The Numbers Worth Watching
Credit utilization doesn't have to be complicated.
Start with three numbers:
Your balance.
Your credit limit.
Your utilization percentage.
For example:
$900 balance
$3,000 credit limit
30% utilization
Once you know your numbers, you can make decisions based on what's happening with your own credit instead of guessing.
Frequently Asked Questions
What is credit utilization?
Credit utilization is the percentage of your available revolving credit that you're using.
How do I calculate credit utilization?
Divide your credit card balance by your credit limit, then multiply by 100.
For example, a $900 balance on a $3,000 limit equals 30% utilization.
Is 30% credit utilization good?
The episode discusses keeping utilization below 30%, with 1% to 9% presented as the target range.
Do I need to carry a credit card balance to build credit?
No. You don't need to carry a balance and pay interest to build credit.
Can making a payment before my statement closes lower my utilization?
The episode discusses making payments during the billing cycle and before the statement closes as one way to lower reported utilization.
Can a higher credit limit lower my utilization?
It can lower the utilization percentage if your balance stays the same. For example, a $900 balance represents 30% of a $3,000 limit but 15% of a $6,000 limit.
Can closing a credit card affect my utilization?
Closing a paid-off card can reduce your total available credit, which may increase your overall utilization ratio if you still have balances on other cards.
Keep an Eye on the Number
Credit utilization is one of those financial numbers that's easy to overlook.
But once you understand what it means, the calculation is straightforward.
Know your balance. Know your credit limit. Know your utilization.
And remember, you don't need to carry a balance and pay interest just to build credit.
Have a money question you'd like Ralph and Juliet to discuss?
Send it to:
https://www.becomingfinanciallyconfident.com/voicemail
Watch Becoming Financially Confident live every weekday at 11:30 AM Eastern:
https://www.becomingfinanciallyconfident.com/live
Licensed Public Accountant
Ralph V. Estep, Jr. is a Delaware-based Licensed Public Accountant (LPA), author, rancher, and media host with more than 30 years of experience in finance, taxation, and small-business leadership. As the founder of Saggio Accounting+PLUS and the creator of the Ask Ralph Media network, Ralph helps entrepreneurs, creators, and everyday families replace money confusion with clarity, confidence, and practical next steps — without shame and without hype.
Ralph's work blends deep professional expertise with a coach's mindset and a communicator's heart. He has held leadership roles across public accounting, financial institutions, law firms, and technology organizations, bringing a rare combination of traditional accounting rigor and modern systems thinking to the people he serves. A graduate of the University of Delaware and Wilmington University (MBA), he is known for turning complex money topics into simple, repeatable frameworks that help people make wiser decisions and build lasting financial stability.
He is the host of Becoming Financially Confident, a live weekday show built on a single conviction: most money stress is not a character problem but a systems problem, and shame is what keeps people from fixing it. The show grew out of Financially Confident Christian, which Ralph hosted for more than 1,200 episodes across eight seasons and earned national recognition. The new show offers the same host and the same feed, opened up to a wider audience.
Through Ask Ralph Media, Ralph hosts several other programs. Grit and Growth Business… Read More
HSA vs. FSA: Which Should You Pick in 2026?