The Dollar Job Framework: How to Discover Where Your Money Goes

 Apple Podcasts

 Spotify

 YouTube

 Rumble

 Podurama

 Amazon Music
Hosts: Ralph Estep Jr, a licensed public accountant of over 30 years + Juliet, a first-time entrepreneur.
Here's what we got into today:
- A Maryland law banning those unsolicited home equity loan checks starting October 1, and what to look out for yourself
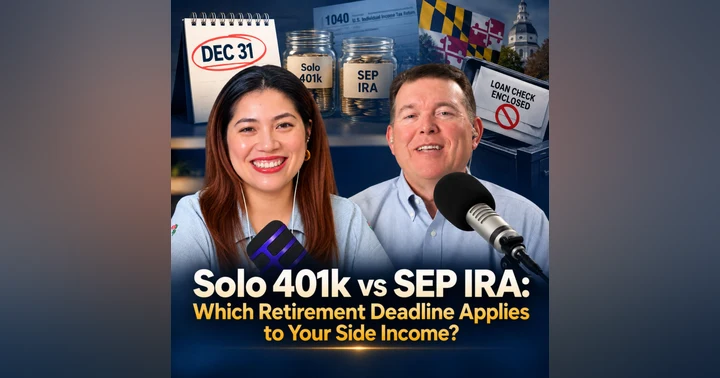
- The December 31 deadline to open a Solo 401k or SEP IRA and maximum your money if you picked up side income this year
- Dollar Job Framework: Discover your net worth and get clarity on what you want versus what you do, then Design the financial life you want
- This week's Money Move: identify all your subscriptions and cut at least one
Got a money question for me? Send it to us at becomingfinanciallyconfident.com/voicemail.
Or come watch us live every weekday, 11:30 am ET at becomingfinanciallyconfident.com/live.
Links mentioned in this episode:
becomingfinanciallyconfident.com/wallet
becomingfinanciallyconfident.com/discover
becomingfinanciallyconfident.com/quicken
becomingfinanciallyconfident.com/stamps
Follow us on our socials:
00:00 - Untitled
00:23 - Retirement Account for Side-Business Income — Open by Dec. 31
05:06 - Opening a Retirement Account for Side Income — Solo 401(k) Options for 2026
11:15 - Are You Getting Your Full 401(k) Match? (True-Up & Quick Money Check)
18:03 - Discovery — Tracking Where Your Money Goes
28:51 - Organize Your Expenses: The Five Dollar Job Families
33:33 - Discovery: Track Where Your Money Goes
41:27 - Discover: Where Your Money Is Going
51:40 - Weekly Money Move: Audit Your Subscriptions
54:54 - Stamps.com — Mail from Home (Sponsor Segment)
Juliet Chuang
Today, you might have an unsolicited loan check sitting in your junk mail.A check from a lender you never contacted offering you money you never asked to borrow.And if you signed the back, you could put your home on the line.One state just made that kind of a loan illegal.Also today, if you made money from a side business this year, there's a retirement account you need to open before December 20th 31st.And two questions you can ask about your 401k to make sure you're getting the full employer match.And then like we promised yesterday, we're picking up the dollar job framework back up, looking at the dream, then moving into discover and design.Because you can't make a good plan for your money until you know where your money is going.
Ralph Estep Jr.
Becoming financially Confident.
Juliet Chuang
Welcome to Becoming Financially Confident, where we're breaking free from money shame.One conversation at a time.We're live every Monday through Friday at 11:30am Eastern.
Ralph Estep Jr.
Well, good morning, everybody.I'm Ralph Estep Jr.I'm the licensed public accountant on the show with 30 years of doing things in the trenches.And like, somebody just told me Ralph was right.That felt really good today.
Juliet Chuang
And I am Juliet.I'm a regular person with all of the questions for Ralph because you might have them, too.
Ralph Estep Jr.
Yeah, we're two very different people having conversations about the things that affect our money.And.And I'd be willing to bet they probably affect your money, too.Now we've got two house rules we always go by here on the show.There's no shame in anybody about money.What happened yesterday happened yesterday.Today's a new day, and nobody's going to be judged for what they didn't know.Our whole goal with this show is to empower you and equip you so you can become financially confident.
Juliet Chuang
And if you have a question that you want us to have a conversation about online, send it to us@becoming financiallyconfident.com, no question, is off limits.
Ralph Estep Jr.
Sorry about that.We just had a little bit of a technical glitch there.But wherever you are on your financial this is why I love doing live.Wherever you are on your financial journey, know that you're not alone.We just lost our Facebook feed, but we're still good on the other channel, so we're going to continue moving forward.
Juliet Chuang
Yes, sounds good.Ralph, some of our listeners may have gotten a check in the mail for money they never asked to borrow.It looks like free money, but it could actually be a loan that uses your home as security.So that's dangerous.What Happens if they sign that check.
Ralph Estep Jr.
Yeah.This is one of those junk mail things that a lot of people aren't aware about.And I haven't seen a ton of these lately, but this showed up in the newsfeed, and I was like, you know what?We need to talk about this today.
Juliet Chuang
Right.
Ralph Estep Jr.
What this basically is, it's a home equity loan that you're basically signing by signing this check.Now, the state of Maryland here, not far from Delaware, actually bans this, and they've signed new legislation that starts October 1st, because what they're saying is, you didn't ask for this.You didn't approve any of this.And unfortunately, it's taken people by surprise because they think, oh, I can get this money.I just signed this check, and they send it back.They send me the cash, or they direct deposit it.It's a big deal because you're putting your home on the line.So if you.Go ahead, Juliette.
Juliet Chuang
I was just gonna say, I think it's so crazy that just by signing this one thing and mailing it back, it's so easy to put your home on the line, because you would have.You would imagine that it a couple more steps to get that to happen at all.
Ralph Estep Jr.
It does.And I think in defense of people who would say the same thing, I think this is the start of the process.I think that's the thing we need to understand.But it's one of those things where if you're not paying attention, you might think it's just a personal loan or some kind of line of credit that isn't attached to your home.But that's the sinister part of this.So here's my direction on this one.Go find that pile of mail that you were about to throw out for me on the kitchen counter.My wife has this basket.It has Ralph's mail in it.And to be very candid with you, there are some days I don't go through that for several days because it's kind of funny.The office here and my home have two separate addresses.So the stuff that comes to the office, I probably pay more attention to, but the stuff that comes to the house, I don't so much.But if there's a check in there that you didn't apply for, shred it.Don't just toss it because it might have some personal information.Another thing you can do is you can dial this number, 1-88-8-8,5, opt out again.I'm going to give you that number.Mark from Practical Prepping said Ralph, when you talk about things on the show mention them twice.So this is our second mention.It's 1-888-5- opt out and that gets your name off these mailing lists for good.And again, like I said, Maryland had Senate bill number 582, which is banning unsolicited secure checks effective on October 1st.That's actually a Maryland statute.And if you do it in Maryland, it's going to be a misdemeanor and they can charge the person up to $500 for the mailer.So this is an area, again, this is buyer beware or signer beware.Just pay attention to your junk mail because that stuff might need to be shredded.
Juliet Chuang
Yes, If somebody had real side income this year and wants to shelter some of it.Ralph, is it too late to open a retirement account for 2026?
Ralph Estep Jr.
No, it's not.And in fact, this is the very conversation I just had with a client of mine.He's having a really good year.And I said to him, I said, you know, one thing we talked about a couple times this year is we've got to set up that retirement account for you.
Juliet Chuang
Right.
Ralph Estep Jr.
As long as you get it set up and funded before the end of the year, you can take advantage of this.And a lot of people don't know about this.When it comes to side income, there are a couple of different versions of this.One of the things is called a solo 401k solo 401 solo one.And it kind of works the same way you would imagine it's a solo.So it's just for you, it's a 401k plan.The benefit to the 401k plan.So let's take a minute and talk about what this is.A 401k plan is basically your way of putting pre tax money into an investment account.Pre tax, meaning that you don't pay tax on that money until you take the money out.
Juliet Chuang
So if you put $1,000 in, then you're investing with $1,000.You're not investing like 900.
Ralph Estep Jr.
Correct.And the benefit to that, honestly, is that you get a direct return on your investment right away.Let me explain what I mean by that.If you pay taxes, in other words, if you have taxable income, the minimum tax rate is generally 12% for most individuals and it goes up to 37%.So for sake of an example, let's just say you're in a 22% tax bracket and let's say you live in a state that has a state income tax.Delaware's tax is about 8%.So if I take the 22% federal and I take the 8% state, that's a 30%.
Juliet Chuang
Right.
Ralph Estep Jr.
If I put money into a retirement account, I am saving 30% of whatever I put into it from day one.That's a 30% return on your investment from the beginning.There is no bank in the country that's paying 30% interest on your investments.
Juliet Chuang
Right.
Ralph Estep Jr.
So this is one of those things where to me it's a no brainer if you've got the money.Now again, you got to look at your cash flow.We're going to talk a lot today about discovering where your money's going and understanding and building a plan.But if you've got the money, if you're making money with your side business, if you're making money with that now, if you're already contributing to a 401k through work, you can't double contribute.So you have to be careful.In other words, if you've got a traditional 9 to 5 job where you're getting a W2, if you're maxing out the 401k over there.When I say maxing out, I mean putting in the total amount that the IRS allows you for the year, not necessarily a percentage that your employer allows.So for example, this year I think the 401k is about $24,000.That's what you can legally put in for individuals.Right.So if you're not putting in 24,000 in your 401k at work, first of all, if you can afford to, you should be, especially if they're doing a match.I've talked about this on the show before.If your employer is matching, it's like walking over $100 bills on the sidewalk.But if you aren't doing that, if you're self employed, this is a great time to have a conversation with somebody like me and listen.Reach out to me.You can go to becomingfinanciallyconfident.com you can schedule a call with me.We actually set these up for clients.We have a relationship with a very great payroll company and they actually established these solo 401k plans.And, and these plans are not expensive.They give you basically 27 different investment options you can pick.And it is a great way to save money and it doesn't cost a lot.So that's why I put this in for today.Because this is one of those things where if you can get a 30% return on your investment right from the jump to me, it's amazing.Let's do It.
Juliet Chuang
So quick question here is for, for side hustle income or side income.Is a Solo 401k the only option that they have in terms of retirement accounts?
Ralph Estep Jr.
Absolutely not.You can also do what's called a SEP ira, which is basically a self employed ira.There's some different nuances to that.With those, you can put up to 25% of whatever the income is in the business that self employment income you can do.And you might just say, look, Ralph, I don't have a lot of money to put aside.You can do a traditional IRA contribution up to about 7,000 or 7,500.You know, this is where I get in trouble, Juliette, because the tax software always makes sure that Ralph knows what he's talking about when I'm meeting with clients.So that's a legitimate discussion you have to have.If you're not going to put more than what the traditional IRA contribution is, don't spend the money to build a 401k plan because you're not going to really get anywhere with it.
Juliet Chuang
Interesting.Okay, I feel like we should have a follow up conversation just being like as a person with side income, how should they make those considerations or make those decisions between a Traditional IRA vs Solo 401k vs SEP IRA?Unless Traditional and SEP is the same thing.
Ralph Estep Jr.
No, they're, they're a little bit different, They're a little nuanced.But what, what this really comes down to.Juliet, if you are self employed, you need to get on my calendar because there are things that I can help you with with self employment tax.There are things I can help you with with retirement planning and just making sure that your money is maximizing for what you need.But if you've got side in, if you've got side hustle income this year and it was meaningful, get in touch with me or call a brokerage this week and ask to open a Solo 401k or like Juliet said, a SEP IRA.They just had to be open before December 31st.You can find a SEP IRA until tax filing deadline.The Solo 401k has to be funded this year.
Juliet Chuang
Got it.
Ralph Estep Jr.
This is one of those things that it's going to save you a ton of money.So go do that.I'm not making it extra homework for this week.But if you're a freelancer and if you're a side hustle, if you're self employed, this is a great way to put aside some money for retirement.Because guess what, like I talked about a couple of weeks ago, the retirement horizon is Closing in on you.
Juliet Chuang
Oh, yes.
Ralph Estep Jr.
Don't wait to the last minute.
Juliet Chuang
Sounds good.So this one is a quick money check.Not necessarily news, but it could be worth a phone call.How do you know if you're actually getting all the money your employer is willing to put into your 401k?
Ralph Estep Jr.
I think we've got a theme here.What do you think, Juliet?
Juliet Chuang
I think we have a theme too.
Ralph Estep Jr.
So this is a nuanced thing and what I'm talking about here is if you are lucky enough to work for a company that matches what you put into the retirement plan, you have to pay attention to your pay stub.Because there's a thing called a true up.We do payroll for about 100 clients a week.There is a true up, meaning that if.Let me give you a simple example.Let's say Juliet works for me and Juliet decides she's going to put 3% of her compensation into the retirement account.
Juliet Chuang
Right.
Ralph Estep Jr.
Basically what happens is each time Juliet is paid, 3% goes into that money that she's putting in.And as the employer, I'm matching that 3% as well.
Juliet Chuang
Right.
Ralph Estep Jr.
But let's say for some reason Juliet gets a bonus or Juliet does something to increase her compensation.
Juliet Chuang
Right.
Ralph Estep Jr.
The 3% match is based on your compensation.So you've got to make sure that your employer and I don't see this a lot with the bigger employers and the companies that are using traditional payroll services like the ADP or the paychecks, or we actually, all of our clients, use a company called sure Payroll.Those are automatically doing the true ups.But if you're working for a smaller company and the HR person is Sally down the hall, this is one of those things you might want to have a conversation and say, look, are we making sure that the match is correct?So this is what you need to do.Log into your 401k portal.Just about everybody I know that has a 401k plan, they give you a username and password so you can go and check.And I encourage you, check on this.Make sure the money is getting put into your account or call HR and ask them two questions.Does my plan have true up matching contributions and.And am I on full pace to get to my full match by December 31st?This is one of those things where, again, this has to be done in the current year.You can't wait till after the first year.So this is a great time to look at your pay stub and have a discussion with yourself and say, could I put a little bit more into retirement Am I getting to the total that the company is matching?Because this is Ralph's truism on this thing.It's a little bit of a Ralph rant.If you're not putting in at least what the business is matching, you are leaving money on the table.It is literally stepping over top of $100 bills.
Juliet Chuang
I agree with that.I think that's the most important thing.Yeah.
Ralph Estep Jr.
Thank you, Julia.And it's a lot of people don't think about that, but it's a huge one.And if you compound that year after year after year, this number grows quickly, very quickly.So just make sure you're asking the questions.Make sure you're talking to HR, looking at your payroll portal, making sure your 401k is being funded.And here's a problem a lot of people don't think about.Sometimes you have a bump in the road, you gotta get more cash in your pocket.So maybe you turn off the 401k or you turn down the percentage sometime during the year.Go check that.Because you still have time to make up the difference, to make sure you're contributing the match.It might make a little bit leaner paychecks for the next few months, but it's something that's going to pay you in dividends.And like we talked about, I waited 20 extra years to get my retirement funding.And even at $500 a month, it cost me a million dollars in what I could have invested.So that's how this money, how this math and this compound interest really works.
Juliet Chuang
That's true.So double check all of that.If you are employed by somebody, just Double check your 401k even before the month ends.Hopefully.That way you have enough wiggle room to make any adjustments as needed.
Ralph Estep Jr.
Absolutely.It's very important.Well, let me ask you this question.When's the last time you actually looked at your credit score?Here's what I found.Most people avoid it.And it's not because they don't care about their credit score.It's because they're scared of that number.And here's the sobering statistic.The Federal Trade Commission found 1 in 4 people have an error on their credit report.5% Are paying more on loans because of a mistake that isn't even theirs.And if you keep the blinders on, you can't dispute what you won't look at.Which is why we've got an affiliate relationship with WalletHub.WalletHub is absolutely free.It updates your credit daily, and it tells you specifically what's dragging Your number down.If you're interested in finding out more information about WalletHub, you can go to becoming financiallyconfident.com wallet again, that's becomingfinanciallyconfident.com wallet.It's free and it's really a great service.
Juliet Chuang
So we are in this section of called segment called the breakdown.And so this is a continued conversation on the dollar job framework, which we've been doing for about two weeks now.So this is the third time we're talking about it.So before we really get into today's breakdown, Ralph, can you give us a quick reminder where we last ended off?
Ralph Estep Jr.
Absolutely.I'm going to talk about that in a second.But we did create another handout for you and I'm going to encourage you right now.You can take time to go grab it.You go to becoming financiallyconfident.com discover again, that's becoming financially confident.com discover.Enter your email address, hit agree.It's going to send you an email.You click on that and you'll get our discovery package.Just about three pages.We're going to talk a lot about how to define and discover where you are today.So encourage you to go get that again, that's becoming financiallyconfident.com discover.And if you're listening to this after the after the live show, we'll put that in the show notes.But getting back to Juliet's question, I.
Juliet Chuang
Was going to say Abby can.Our producer can also put it in the chat right now too.So it's easy click.For everybody who's hanging out here, we.
Ralph Estep Jr.
Absolutely rely on Abby.So Abby, thank you so much for joining us every day.She is keeping the chat going and we really do appreciate it.
Juliet Chuang
Yes.
Ralph Estep Jr.
So what you were talking about, Juliet, is how do we start this dollar job framework.The whole idea behind this is we're giving every dollar a job and we're defining what those things look like.So we started off with the dream.If you missed last week, you can go back and check that out.We'll put a link in the show notes.But the dream is what you want your money to make possible.What is it that thing that you say if I did this, I could do that.What is that dream?So we started off with a dream and then we got into define and that's that number and a date attached to it.Because what we realized is like with any other GPS or anything like that, you need a destination and you need a location.
Juliet Chuang
Right.
Ralph Estep Jr.
Today we're going to get into the specifics of this.And we're going to talk about discovery.Now, I will tell you, Juliet, the discovery phase, this one sometimes hurts a little bit because you're actually going to take a look at where your money is going.
Juliet Chuang
I will say, like, the discovery, to me, the biggest barrier is the emotional part of it.It's like, oh, now I'm going to face my numbers.Right?And so, at least for my plan, I haven't started it yet.Well, I kind of started it, but I haven't, like, really done everything in one go.But I think that is the way to go.Like, instead of doing five minutes every single day, right.I am just going to rip the band aid off.And maybe I say I'm going to rip the band aid off in three parts.And then I want to be able to read through everything.That's my plan.But so my suggestion for everybody is just kind of check in with yourself emotionally and mentally.Like, if this.If this step, the discover phase, scares you, why does it scare you?Right.And then try to think of it, well, how do you want to handle this?Do you want to handle it in many parts or, like, small parts?And just also imagine at the end of the discovery, then you can get closer to your dream.
Ralph Estep Jr.
Just remember, there's no shame in this.This isn't about shame.It's about finding the truth.Because this very situation is, until you know the truth, and you know, I've said this on the show before, until you know the truth, you're never going to be able to get to that point of becoming financially confident because you don't know where your money's going to.And remember, this shows house rule.No shaming anybody about money.This is the exact same situation.This is all about building the framework of how to figure out where your money is going.And this is really the source of truth.So let's get right into what I call the discovery checklist.What does that look like?And it's going to be a couple components to this.It's going to start off with discovering what your income actually is.And I want everybody to understand what your income actually is for this is not what your salary is when they hire you for your job.That's not what I'm talking about.I'm talking about the money that you actually get in your paycheck, the net pay, because you can't pay Social Security, after all.Yeah.After all your taxes, because you can't live on your salary.You live on the direct deposit that you actually get.And that ties a lot of People up in knots, especially younger people who get hired out of college and they say, oh, I got this great job, they're going to pay me $80,000 a year.Well, guess what, you're not going to see $80,000 a year in direct deposit.You're going to probably see about 70% of that.So that's where we need to start off again.We're discovering what the income side is.Because what we're going to do in this whole framework is we're going to start off with, here's the actual dollars that are coming in real dollars, that is the after tax dollars, that's after the FSA dollars, that's after the retirement contribution dollars.These are the real dollars that are hitting your bank account either on a weekly, bi weekly or once a month basis.
Juliet Chuang
And this is why when we talk about side hustles, we also have those conversations about like, what are, what is, if you're using a platform, what is being taken out of that?What are your expense, you know, expenses is another part of the equation when we're talking about Discover, but specifically for like platform and taxes, like who's taking your money first?That's why we talk about that in, when we have those conversations.
Ralph Estep Jr.
Yeah, because you got to understand, do you have enough withholding?Are you going to end up owing tax?Maybe you have too much withholding and you're going to get a big refund.Well, that's money you could actually use as you go.So we'll talk as we move along in later weeks and later, later months about this, of how to make that income exactly what it needs to be based on how much you, you actually need to be setting aside for taxes.We'll also talk about, we've talked a lot about 401ks today.So once we get to the income piece, that's kind of the top of the chart here.If you get this handout we're talking about, you're going to see, I put that right onto the handout.But then we get into expenses.This is where your money is actually going.These are things like debt payments, your mortgage payment, your rent payment, any kind of credit card payments.Those are all the expenses.Then we have your subscription.We talked about our money move of the week.We're going to get to that here at the end of the show.But this is where you're going to see those things, your subscriptions.It's also where you're going to see what you're putting aside for savings.You're going to see what you're putting aside for giving?And here's the thing you're really going to notice when you start the discovery phase, you're going to find those spending leaks where you don't realize where your money is actually going to end.I'll give you a little hint.Tomorrow we're actually going to have a conversation with a friend of the show.Her name is Kay.And she asked me a question.She said, ralph, how do you know the difference between needs and wants?We're going to actually have her join us on the show tomorrow, and we're going to work through that together.How do we get to needs and wants?But this is where you're going to find us in the discovery phase.What are those spending leaks where you don't realize the money's going?And the other thing you're going to find is those irregular bills.Those are things like they don't happen all the time.Maybe a doctor's visit that you go to once a year, or your insurance payment that maybe is once a quarter, or your homeowner's insurance or your property taxes.When you discover where your money's actually going, and that's why this is so critical, then you can start to design where each dollar is going to go.But until you realize where it is, you're going to have a hard time getting there.So I want to get into a couple more things on the discovery checklist.Again, we're talking about income.We also need to look at fixed expenses.Those are things that we all know about.The rent, it's a fixed number.The car payment is a fixed number.If you have a mortgage, that's a fixed number.If you pay for insurance, generally, that's a fixed number.There are also variable expenses like grocery store trips.It's not going to be the same every week.Your utilities could be a variable expense.We also have to make sure we're putting our debt into that.We're putting our savings into it.Like I said, giving subscriptions and those irregular expenses.Now, I want to throw a couple forgotten expenses on her because when Julie and I were preparing for today's show, she said, ralph, one of the things that you could give the audience would be really helpful is what are some of those forgotten expenses that people don't think about?So, Juliet, because you asked, here is the results.These are things like car registration.
Juliet Chuang
Okay, let's see.
Ralph Estep Jr.
A lot of people don't think about that because maybe that's once a year you have to go to the motor vehicle, like in Delaware, for Example, Delaware is kind of interesting.I get this, I got a new vehicle and I think my registration is good for something like eight years.Now you're paying for that up front.But you don't have to do that every year.If you've got a different situation in your state, then you got to be thinking about that every year.Maybe you have to pay a car registration in some states.South Carolina and some of the states in the south actually charge you an annual tax for your car.I don't.Do they do that in California, Juliet.Like a personal property tax on your.
Juliet Chuang
Car, car registration every single year.
Ralph Estep Jr.
Okay.Yeah.And some states actually charge you a tax based on the value of your car.But that's one of those forgotten expenses.Another forgotten expense is annual insurance add ons.Maybe you have to add something to your insurance.Here's the one that a lot of people miss and Ralph's guilty of this one too.And that's those yearly billed subscriptions.You signed up for something but it only bills that credit card or only hits your bank account once a year.This is where you've got to find those things and make sure you've got those considered.Because here's what's going to happen in the dollar job framework.If you're not planning for that, then you're going to have a shortfall.Here's another thing a lot of people don't think about.How about holiday and gift spending?I don't know about you Juliet, but my kids, my two boys and now the grandson is going to expect some gifts.Maybe birthdays, holiday gifts, travel.All of those things you don't necessarily think about because you don't see them happening every week.You don't see them sometimes.They only happen maybe once or twice a year.But be aware of those annual dues is another one.Maybe you're a professional patient.Go ahead.
Juliet Chuang
Oh, I was going to ask you like as people are going through their discover, do you have a recommendation where they should calculate all of this like on a spreadsheet?Or do you have a tool or do you recommend paper and pen?
Ralph Estep Jr.
Well, I think right now paper and pen is great because you visualize it.And that's why we put together this spreadsheet that you can download.It's at that point becomingfinanciallyconfident.com discover.I put together a little grid that you can use.Listen, here's what you need to use.You need to use what works for you.If you want to go and build a spreadsheet, fantastic.If you Want to go get software?We're going to talk about Quicken Simplify a little bit later in the show.That's fantastic as well.Making sure you're looking at every source of where money comes out of your account, whether that's your checking account, your credit card statements, PayPal, Venmo Cash app.That's the thing a lot of people miss.They don't think about the PayPal, they don't think about the Cash app, they don't think about the Venmo.And then all of a sudden they're like, I don't understand why I'm short.Well, because you didn't consider these other things as we talked about yesterday with.
Juliet Chuang
That is definitely important because when I. Yeah, what were you saying, Ralph?
Ralph Estep Jr.
No, it seems like we're having a little technical glitch where there's a little bit of a delay.So I apologize ahead of time.Go ahead, Julia.
Juliet Chuang
No, no, I was going to say, I feel like you were trying to say something too.
Ralph Estep Jr.
Yeah, What I was saying is we talked about pets yesterday, annual vet visits.Those things need to be factored into money being spent, activity fees, any of those.Maintenance on your home, maintenance on your car.All those things a lot of people don't think about.And then you're like, oh, I hadn't planned for that.Yeah, that's right.We do have to do this.We have to get our car oil changed or we have to get the brakes done.All of those things are what we need to understand in this discovery phase.And that's why I'm a big proponent.And it's a little bit of work, but go look at 12 to 18 months of where your money actually went.Start with 30 days.That's going to give you the immediate things, but I think you need to expand that out a little farther because there could be those one off things.You don't realize holidays is a big one.A lot of people don't think about how much they actually spend on the holidays and they don't think about, well, maybe you've got grandchildren, you've got children, each of them have a birthday throughout the year.You've got to really be paying attention to each of those things as you go.
Juliet Chuang
That is absolutely, absolutely right.So that's like kind of in the discovered phase.So once everybody has gone through that, what do you think?What would you say is the next part?
Ralph Estep Jr.
So the next step, once you've got all of those things listed out, I would literally write them out.This was this expense.Here's what it was this is this expense.And then I want you to put those into the five job families.And we talked a little bit about this last week.Every job, every dollar that you're spending needs to go into a family.And we're going to go through those families again.Those.That's the survival family, the stability family, the future family, the joy and the generosity.Each one of those.So in other words, survival is I've got to have a roof over my head.So that's your rent or your mortgage.Survival could be your transportation costs because you've got to be able to get to and from your job.Survival is you've got to have money for the grocery store.
Juliet Chuang
Yes.
Ralph Estep Jr.
Then you've got your stability things.That's your emergency fund you're putting money into.Those are the things that stabilize your world future.Those are the things like your savings, your 401k.Those things you're putting aside for the future, the joy.Because listen, if we don't put any joy into our world, this isn't going to work.This is why I don't like the word budget.I use intentional spending plan.I use the dollar job framework.Because you've got to build into this thing joy.Now, you can't spend all your money on joy.You can't say, I'm just going to skip the survival, I'm going to skip the stability and hey, who cares about a future?And just put it in joy.That's not going to work either.And then like I said last week, don't forget generosity.I think that everybody needs to build into their dollar job framework some level of generosity and you decide what works for you.I'm not going to sit here and tell you, as a Christian person, I think the Bible is very clear that 10% is the minimum.But that's Ralph speaking.Whatever generosity looks for you, and it doesn't have to be charitable generosity.Juliet mentioned yesterday, sometimes she wants to help out friends, sometimes she wants to help out family.That could be generosity.But you need to think about, now that I've written down all of these things, what family do they fit into?Because you're going to start to put together a schematic of where you're actually, is, where your money's actually going.
Juliet Chuang
This is going to be a very intense, intense phase.But I think like you said, it's so important.It's something that I also need to go through.
Ralph Estep Jr.
Yeah.And like I said, it's going to conjure up.You're going to feel bad, you're going to say, I can't believe I spent this much, but get through those things.Because that discovery, that clarity, that understanding where your money is going, it will get easier.Because once you know it, you know it's one of those things I talk about all the time in a couple of my other things that I do is like when you hide it in the dark, it stays there, it grows, it metastasizes, for lack of a better way of saying it.But when you bring it to the light, you see it.And this is why we're doing our money move of the week.It's all about those subscriptions, knowing what subscriptions you're paying for.That's why I put that as number one on the discovery checklist.Because so many people have no idea where their money is going.I was thinking about it this morning as I was exercising.How do I really convey this message today?
Juliet Chuang
Right.
Ralph Estep Jr.
Where you really get the value from discovery is not in the big things.Because most people know what their rent is, most people know what their mortgage payment is, most people know what their car payment is, most people know what they're spending on fuel and gas, you know, and groceries and all those type of things.But it's those irregular expenses, those one off things, those subscriptions.You didn't realize that's where you actually will find value in this thing.Now I want to spend a little time and talk about what fits into these categories because as you're working through this, you're going to write next to that one of these things.What family.They fit into every single expense, right?Every single expense needs to be assigned one of these.Survival, future, joy, all of those type of things.We talked about stability.So survival, stability, future joy and generosity.
Juliet Chuang
Yeah.
Ralph Estep Jr.
Yep, that's really important.Again, I would encourage you download our tool.It's@becomingfinanciallyconfident.com Discover because I've laid it all out here in black and white.You can download that tool.It won't cost you a dime.You just give us your email address.Again, that's becomingfinanciallyconfident.com Discover I know I sound like a broken record, but I think it's so important because this is if we think about this whole dollar job framework, it is the critical part of this.We had to start with the dream.We had to talk about how do we define what that dream looks like.But this discovery phase, everything else that we do, everything else that we talk about as we move forward into the other phases is going to be based on where Your money is actually going.So remember survival?Those are things like housing, food, utilities, and transportation.A lot of people say, well, Ralph, why is transportation survival?Well, if you can't get to and from work, you're not gonna be able to make money.We talked about starting the whole equation with income.Well, if you can't get to your place of business, then you gotta start there.So that's super important.
Juliet Chuang
Right?
Ralph Estep Jr.
Those are the survival things, and those are the things from a blunt standpoint.I was interviewed for an article that's gonna come out next week, and they said to me, there's this old adage of percentages.You spend 50% on this category.30 And 20, and then 20.
Juliet Chuang
Yeah, yeah.
Ralph Estep Jr.
And, you know, they said, well, Ralph, do you believe it?I say you.I don't know that that fits anymore.
Juliet Chuang
Why not?
Ralph Estep Jr.
Well, I'll tell you why.Because depending upon where you live, Juliet lives in California, right?Juliet's cost of living in California is higher than my cost of living here in Delaware.I guarantee it.In fact, I would be willing to bet that her housing costs, utility costs, and transportation costs are higher.So if 50% works for me, it might be 60% for Juliet.And I think the problem, the reason I don't like that equation is that it puts you into this belief where, well, if I'm spending more than 50%, I might be doing something wrong, right?You may not be doing anything wrong.It might be a function of your income is low based on the real cost of living where you live.
Juliet Chuang
And that's like, oh, sorry, finish your thought and then I'll hop in.
Ralph Estep Jr.
No, I'm done.I'm just saying, like, I think it depends.And that's why I like this plan of putting these five families together.Kind of sounds like a mafia thing.Like, we're talking about the five families, but that's really what we're talking about.Because all of these things have to be touched.You have to survive.You need to have stability, you need to build a future.You need to have joy, and you should have generosity.
Juliet Chuang
Right?Right.I like the.I mean, I've definitely heard of the 50, 30, 20 rule.Maybe.Maybe we should just say like a rule of thumb instead of like a rule.Because, you know, what you said is right, where if.If depending on your cost of living, it may not fall within the 50, 30, 20 rule, but it is a good place to start to gauge, right?Then you can say, oh, I actually don't.I don't need to live in a place that takes up 70% of my income.Right.Like, then you can make adjustments from there.
Ralph Estep Jr.
Yeah.And I think that's the whole key to this thing, because you have to understand the survival expenses are going to be a higher percentage of your income, probably.
Juliet Chuang
Right.
Ralph Estep Jr.
But until you discover what you're actually spending, how can you make that comparison?Should it be close to 50%?Probably.That's probably a fair number to use.The second one is stability.And a lot of people skip this one.They're going, yeah, but Ralph, you know, I do.Surviving is.And listen, you might be in a place right now where you're just having enough to survive.I get that that is a season of your life, But Juliet just said something really interesting, and she said, if you look at this and your survival is 70% of your spending, you may have to have a difficult conversation.Am I in a place where I'm making enough money to live, Where I'm actually living?And that's not an easy conversation to have, but it's a realistic conversation to have.
Juliet Chuang
And it works in so many different ways.Right.Like, if you see that maybe 40% of your money goes towards joyful in the joyful family, then you're gonna be like, maybe I have just been letting myself feel really good.Maybe like too good.At the cost of.At the cost of what?And you have to decide that.That's the thing, though.
Ralph Estep Jr.
Yeah.And again, what we're talking about is clarity.We're talking about intentionality.So you're going to have survival, stability, or things like that emergency fund, because we have to be building margin for ourselves.We have to be putting aside for those what ifs, the blown tire on the way to work.Because that's one of the ones.If you think about it, that blown tire on the way to work kind of becomes a survival thing, doesn't it?Because if you can't afford to get that tire fixed, you can't afford to go to work.But if you build that emergency fund, you're not so much worried about that.This is the place where you're going to do your debt payoff in this model.I'm not saying don't pay off your debts.I'm not saying don't use the avalanche or the snowball method to really get your debt payments down.If you're saddled with credit card debt, this is a stability that you're helping to build.It's also a place like Karen talked about, those sinking funds, where you're setting aside money for, hey, I know I'm going to have a car New tires.I know I'm going to have a roof repair.I know I'm going to have that, that annual vet visit.
Juliet Chuang
Yeah, yeah.
Ralph Estep Jr.
Those are really important.
Juliet Chuang
Oh, yeah.I was going to say, like, the way that I visualize it in my brain is that, you know, once I get clarity, maybe, maybe the survival and the stability takes a huge chunk.Right.But then I know, okay, I actually want to find opportunities to further increase my income so I can have even more for joy.But in order to feel good in the different phases of life, whatever happens, I really want to focus on survival, stability.And then.What was the third one?Let me, let me find it.
Ralph Estep Jr.
Real future.The future.
Juliet Chuang
That's.
Ralph Estep Jr.
Yeah, because you have to have a future.If you don't have a future, why do we bother?
Juliet Chuang
Yeah, exactly.
Ralph Estep Jr.
And future are things like we talked about earlier, that retirement account, investments.Maybe your future is you want to go back to school or you want to develop more education or you want to go to training.All of those things are dollars that you're going to set aside that you're building the future.But like you just said, Juliet, you gotta survive first.You gotta build the stability, and then you can fund the future.Once you fund those things, if you think about.It's kinda like a pyramid, right?It's sort of like.It's sort of like the Maslow's hierarchy of needs, to be blunt, is really what we're talking about here.Because if you don't have a place to live and you don't have food, you're not gonna get past.If you can't survive, you're not going to get to stability.And if you can't have stability, you're not going to get to the future.
Juliet Chuang
Right?
Ralph Estep Jr.
Which leads us to joy.And like I said, if you're going to go into this restriction, I diet it.Most years of my life I've been on this diet and that diet and what they call it, the yo yo budgets work the same way.If you start.I know why most of my diets have failed now.I've been in great shape.I'm in a great place right now.I'm down £200 and I've kept it off.For me, it's been almost a year.That is the best I've ever done.Well, the way I finally did that was not say, ralph, you can't do this, and you can't do this, and you can't do this, and you can't do this.Because that restriction is what fought me for so many years of why I struggled with that because every diet to me was, you can't, you can't, you can't.So when I built this dollar job framework, the whole point of what's my dream?What can I do?What can I choose to do?And that's why you've got to build joy into this, build that entertainment, build those hobbies.Juliette likes to travel her.And I've had these conversations, you got to build that into it.Now, again, if you're in that survival, stability, future mode, you might have a very small amount that you can put in the joy.That's the reality.
Juliet Chuang
That's very true.That's very true.So for anybody who is.And like we said, this is just a starting point.We need to all get clarity first, right?So if you sum it up in one question, Ralph, one question, pose it to the audience so then they can focus and, like, get through this exercise, because it's a very mentally taxing exercise.What is the one question you're going to give everybody?
Ralph Estep Jr.
The question is, where is your money going?It's a real simple question.Where is every dollar going?Kind of like, think about it like this.If you owned a big business and you showed up at the factory, let's say you owned a factory, and you walk in the door of your factory, and you've got 100 employees there, right?You've got to know what each and every one of those employees is doing today.What is their job?What is their role?Because here's the thing.If everybody doesn't have a job, that factory is not going to put.Let's say it's an automobile factory.If you don't have somebody working on the automobile line, if you don't have somebody that's putting the tires on and putting the frame together and putting the windows in, every single person has a role.And if one of those people is missing, you're not going to roll any cars.I remember when I was a teenager, I got to tour the GM assembly plant here.It's been torn down since, but it was the coolest thing ever because it started off with an idea.The first person on the line had an idea of they were actually building.I'm going to date myself.They were building Chevy Chevettes.We'll get that out.It was like a little car, but we had to see the process.I was in Cub Scouts, and it was really cool because one of the Cub Scout parents worked at this GM assembly plant.So we started off at the first place on the line, the first place on the Line was they brought in this chassis and it was just a black chassis.It had nothing attached to it.And it started down the line and then the next person.I don't remember all the specifics, but they put this piece on and they put this piece on and then it was so cool.This was back in the early 80s.They had robots that were taking this and putting this on and everybody's, oh, the robot robots are going to take over everybody in the semi line.That's a different discussion.But it was so cool to see this happen.And then this person put on the frame, and then this person put on the trim and then this person put in the windows.I thought the coolest job was the person.The end.Juliet got to jump in the car and floor it and make sure the brakes work.
Juliet Chuang
Yeah.
Ralph Estep Jr.
And I was thinking, now that's the job I want.But you better hope that those folks on the assembly line did their job, because you might be.Then I realized at the end of this, they got like this crash place where these pieces can crash.I didn't see any cars crash.I was there.But your money works the same way.You got to know where your money's going.You got to know what every single one of those jobs is doing.Because if the person that puts the tires on forgets to put the tires on, when that guy goes to test drive it, he's not going very far because there's tires on it.If you do the same with your money, if you don't understand what the job is, for that part of your money, you're not going to get anywhere.
Juliet Chuang
Yeah, very true.
Ralph Estep Jr.
So this week what you need to do is you gotta have a real discovery pass of where your money's going.I'm a firm believer in putting this on paper.You asked me this question earlier.I like putting on paper because the mind writes something down, it's going to register with you.You could be a spreadsheet person.I think that's fine.But for this particular exercise, and this is why we put together this discovery framework again@becomingfinanciallyconfident.com Discover.Write it down.Write down every single expense, not just the subscriptions, everything that's irregular.Because we're going to talk about that design next week.We're going to talk about how do we design this Once we have the dream, once we have the define what we want to get to.And now we've got this discover piece, the next step is design.But we can't design anything until we know what you're actually spending because we can make decisions once we understand where your money's going.And here's the thing I'm going to tell you, and I've mentioned this on this show many times.Yeah, you will, for you will not realize where your money's actually going.I have never met a single person that said to me, I bet that I spend this.And it was high.It's never high.It's always lower than what you expected.When somebody comes in to meet with me, I do a lot of financial counseling.I do a lot of helping people get back on their feet.The number one thing I say to them, it's usually not an income problem.It's usually a spending problem.This is true of individuals and it's true of businesses.It's where your money is going.
Juliet Chuang
Yeah.
Ralph Estep Jr.
So this week, do a real Discover pass.You've already started with subscriptions.That's this week's money move.So you should already have that done or you're working on that.But add in the rest.Add in those fixed bills.Add in those variables what changes month to month.Is it your utilities?Is it your food cost?Add in those irregular lists that we went through and write it all down in one place.I'm not asking you to have a whole plan right now.This is just raw data.
Juliet Chuang
Yeah.
Ralph Estep Jr.
Here's what I spent.Here's the date, here's the amount.And what family did it fit into?Was it survival?Was it stability?Was it future?Was it joy?Or was it generosity?Because that's what we need.Because here's the thing I'm going to tell you.This is the big takeaway for today.If you don't hear anything else I say, unassigned money usually gets spent by accident.Go back to my analogy of the people at the factory.If they don't have jobs, what are they going to do?They're going to sit around and drink coffee and they're not going to accomplish anything.Right.They don't have an assignment.If your money doesn't have an assignment, it's going to get spent.It's just going to go away.You're going to be like, what happened to my money?Assigned money builds a life on purpose.It's intentional.I can't promise you that this design is going to be finished in one week or two weeks.This is a big deal.This is going to take some time.Yeah, but you can't give a dollar a job if you haven't counted it yet.And that's where this discovery, it might seem Boring.Like, oh, Ralph, this is going to take me forever.I've got six credit cards.I've got this bank account.I use PayPal, I use Venmo, I use Cash app.Here's some tough love from Ralph.Too bad.If you want to become financially confident, you've got to know where your money is going.This is real work.But here's my promise to you.If you put in the real work, you will get real benefits from these things, and they will happen quicker than you think.If you refuse to.If you say, Ralph, look, that sounds good.I'm not going to do it.You're going to be in the same place you're in now six months from now.You're going to be in the same place you're in 12 months from now.
Juliet Chuang
You know, this is a good reminder.I think after our live show today, I'm going to go schedule some money time with me.Maybe I'll just do it two times this week with 40 minutes each.And then.So then that way I know, okay, this is.Time is blocked off.I'm going to do all of this.I'm going to get through as much as I can possible, turn off all the other distractions, and then afterwards, I'll have a glass of wine to release stress and then do it again.And I'm going to.You know what?I am going to do it tomorrow.Wednesday.I'm going to set up another date with myself on Friday and do these two sessions first and see how much I get through.
Ralph Estep Jr.
Here's what you just did, Joy.And I love this.This is one of the things I tell clients to do all the time.Set a money date with yourself.Put it on your calendar at least once a week.
Juliet Chuang
Yeah.
Ralph Estep Jr.
I call it the weekly money check in.
Juliet Chuang
Yeah.
Ralph Estep Jr.
And go and look at what came in this week.Go look at what went out this week.Look at what's going to come out next week.So you don't have those.Those overdrafts like we talked about.
Juliet Chuang
Right, right, right.
Ralph Estep Jr.
Once you start that habit, it might take you 10 or 15 minutes a week.You are going to get huge benefits from that.The dividends on that are going to be amazing.You think investments pay well.This investment in yourself is going to be the best investment you will ever make.
Juliet Chuang
Yeah.
Ralph Estep Jr.
But you got to put it on the calendar.And it needs to be sacred time.It needs to be.I am going to do this every week.So find a time that works for you.Whether that's a Friday, whether that's a Sunday, whatever time when you can be alone, where you can get everything in front of you.The secret to this whole framework, the secret to everything I talk about, is being intentional and being intentional with your time.And Juliet, this is why I truly believe where you're at is where we need to go.And that is set aside that time every week to go make sure you're doing what you need to do to help yourself get to that place of we talk about.What does becoming financially confident mean?It means knowing that no matter what happens, you have clarity.No matter knowing what happens, you know, here's where I'm spending my money.Here's the intention I have.Listen, things are going to happen.You're going to have setbacks in life.Stuff is going to break.The dryer is going to stop drying.The washing machine is going to overflow itself, the dishwasher, the front door is going to fall off.These things happen, right?But when you're planning for these things, when you have a framework, when you're giving every person in that plant a job, then you can say, well, listen, I got a job for that.I got a person who handles that.Do the same thing with your money.
Juliet Chuang
Yeah.So I think that will be good.This is a huge piece of work that everybody should go through.It's kind of a lot, but we'll.
Ralph Estep Jr.
Get through it and we'll do it together.And like I said, go download our tool today.It's becoming financiallyconfident.com discover.Now, while we're talking about that, I mentioned this earlier in the show.Quick question for you.What did you spend last month?We've been talking about this very issue.I'm not talking about what you earn.Most people can say, well, you know, I got about this much in, but what did you actually spend?I've spent 30 years doing this, and I have never once had a person guess that number too high.Almost everybody guesses it too low and they believe it.Well, quick and Simplify connects your accounts.It connects your bank accounts and your credit cards and all of those other things.
Juliet Chuang
And.
Ralph Estep Jr.
And it gives you the answers you need for everything.We talked about that.And then it does the harder thing.It actually shows you what's safe to spend for the rest of the month after the bills, because you build your budget, your intentional spending plan into that, and then you already set aside the savings.If you're interested in finding out more about Quicken Simplified, go to becoming financiallyconfident.com quicken again.That's becoming financially confident.I actually, personally have used this Simplify program.It is not expensive, but it gives you that information so you actually know where your money is going.And once you have that financial clarity, you can make better decisions.And it fits directly into Discover phase of the dollar job framework.Again, that's becoming financially confident.comquicken.
Juliet Chuang
So let's talk about this week's Money move.So this week, this week's Money move is just about subscriptions.I know we talked about the Dollar Job framework, doing the whole discovery thing.You can think about this week's Money move reviewing all of the subscriptions that you pay for as part of that Discover exercise as well.So look through any subscriptions that you pay.Hopefully not daily, but maybe there's like a daily one, a weekly or monthly or annually.And write that all down.And then at the end of the at least cancel one that you do not get the value out of.Okay, I have not done it yet, but it, but, but it's on.It's on my list.
Ralph Estep Jr.
I was going to ask you in the chat, did anybody build their list yet?Did anybody finish the list yet?And this is one of the ones that I have to do as well because I noticed when I was looking at some numbers the other day, I was working on some personal stuff and I said, you know what, Ralph?This is one of those tasks where you preach into the choir, dude, but you're not singing in the same hymnal book.So this is the one I've got to do.So I'm gonna sit down later on this week before Friday and I'm gonna go through my credit card.I actually use one credit card.So it's gonna be super simple for me.And I'm gonna look at what I'm actually paying for.Because I got a feeling I'm paying for a lot of stuff.I mean, just I think about it, with the content creation work, how many AI tools am I paying for?
Juliet Chuang
Oh, you know, that's such a good one because with all of the AI, like if you are doing side hustle on all of this, I think it's so easy to get swept up.Like, this tool is going to do amazing things for you.You should get this tool right.Something that we talked about many, many shows ago is that when you are looking at a new tool and you're like, maybe should I do it?The annual ver.The yearly subscription is, I don't know, like $40 cheaper than if you do monthly.But at that time we mentioned, it is so important for you to test whether you will actually use the tool, whether you'll actually adopt it.So might as well go with the monthly one at the very beginning.And then once you say, oh, this is a.See in my workflow, then you can upgrade to a yearly one.I have made the mistake there of paying for subscriptions for yearly subscriptions on things I end up not using.And I so pissed at myself.I'm mad at myself.I'm like, that's wasted money.That's mine, you know?
Ralph Estep Jr.
Yeah, yeah, because they all add up.And I agree with that.And listen, I am not, I'm not poo pooing on the companies that offer you the discounts for signing up for the year.I get it.But I will never tell anybody to do that unless, you know you're going to use that tool unless you know there's not going to be some.And listen, we talk about AI for a second.AI is changing by the day.So I am not a big fan of that.All those subscriptions add up, though.Streaming services, how many streaming services you need?I like what Juliet said.She said I do this streaming service for a while, then I cancel it and I go to the other streaming service and I cancel that one, I go to another one.I don't.I don't think you realize that this is like death by a thousand cuts.So that's why I thought it was so important.And it falls right into line with exactly what we talked about today that discover.Because this is all part of that.So make sure you're doing that this week and make sure you're getting to the point of where you're actually going and looking at what you're paying for.
Juliet Chuang
Right.
Ralph Estep Jr.
Well, let's talk about this now.We're going about stamps dot com.Now, I've talked about this on the show before.You know, so many of us have that envelope on our desk right now.We know what it is.We're supposed to mail it back, but it's been there for a long time.It's not urgent enough to make a special trip to the post office, but again, you can't throw it away.You gotta do something with it.So it just sits there.Well, that's why I like stamps.com, because stamps.com puts real postage on it from your own printer.You don't have to go anywhere to do it.And the carrier can come and pick it up right where you're at.No trip, no line and no delays.And they give you 30 days for free.And then plans start at as low as 14.99.A month.If you want to find out more about our relationship with stamps.com, you can go to becoming financiallyconfident.com stamps.Again, that's becomingfinanciallyconfident.com stamps.You can use it for UPS and you can use it for FedEx as well.It is a great tool.And listen, I wouldn't put my name on it if I didn't tell clients to use it.So again, that's becoming financially confident.com stamps.Well, let's talk about tomorrow's show, Joy.We got a great one planned for tomorrow.Tomorrow on the show, we're going to have a side hustle corner.We're going to talk about unconventional ways to earn extra income even if you're retired.Now, we're not talking to many retirement people here, but these are side hustles that anybody can do.And then, like I mentioned, Kay is going to join us and we're going to have our explain it like it's broke session where we're going to walk through needs versus wants.Because one of the other things that we're going to do in the discovery phase, I'll give you a little hint.We're going to talk about tomorrow.We're actually going to go into the discovery information you solve, and we're going to put an N or a W next to it.We're really going to get into whether that's a need or whether that's a want.How does that hit you?Juliet, what do you think of that?
Juliet Chuang
I'm really excited to talk to Kay on the show tomorrow.
Ralph Estep Jr.
Yeah, Kay's a younger person.Kay actually works for me, just in full disclosure.And she listens to this show every day.And she said, Ralph, she says, you know, one of the things you should talk about on this show is how do you figure out needs versus wants?And I said, you know what, that's a tough one because I know personally this is something I've battled with.I need this.I need this.I need this.
Juliet Chuang
Yeah.And this is a conversation where everybody has to come with their own, like, how do you think about this?Right?Because there's no one right answer or anything like that.So the conversation with tomorrow truly is going to be a conversation with K. As we try to see, okay, this is, I'm coming in with this definition of what is a need versus a want.Through conversation, will my definition change?Will I have additional perspectives that I will keep in mind for future decisions?So that's the goal for tomorrow.So if you're listening come with your.Your own personal definition.Would love to make sure this is a conversation in the chat tomorrow, too.
Ralph Estep Jr.
Yeah.And be willing to throw some ideas out there, like, hey, Ralph, do you think this is a need or a want?Or Juliet, do you think this is a need or a want?And let's have an open discussion about it because some.I'll give you an example of this.Some people might think that trip to the Dunkin donuts is a need.
Juliet Chuang
Yeah.Yeah.
Ralph Estep Jr.
But is it meat?
Juliet Chuang
So that is it for today's episode of becoming financially confident.
Ralph Estep Jr.
I'm Ralph Estep Jr. And I'm Juliet.And again, if you've got a question for this show, this show is built around your questions.We handle those several times during the week and we'd love to hear your voice.You can go to becomingfinanciallyconfident.com voicemail again, that's becoming financiallyconfident.com join the conversation with us by sending us a voicemail message for sure.
Juliet Chuang
And then tomorrow, join us live@becomingfinanciallyconfident.com live.
Ralph Estep Jr.
Remember, this is becoming financially confident.It's a journey that we're all on.But our goal at the end of the day is to help you break free from money shame.And we're doing it one conversation at a time.So have a great day, everybody, and we'll see you again tomorrow on the show.
Juliet Chuang
Sam.