How to Actually Read Your Credit Report, Plus the Rover Side Hustle
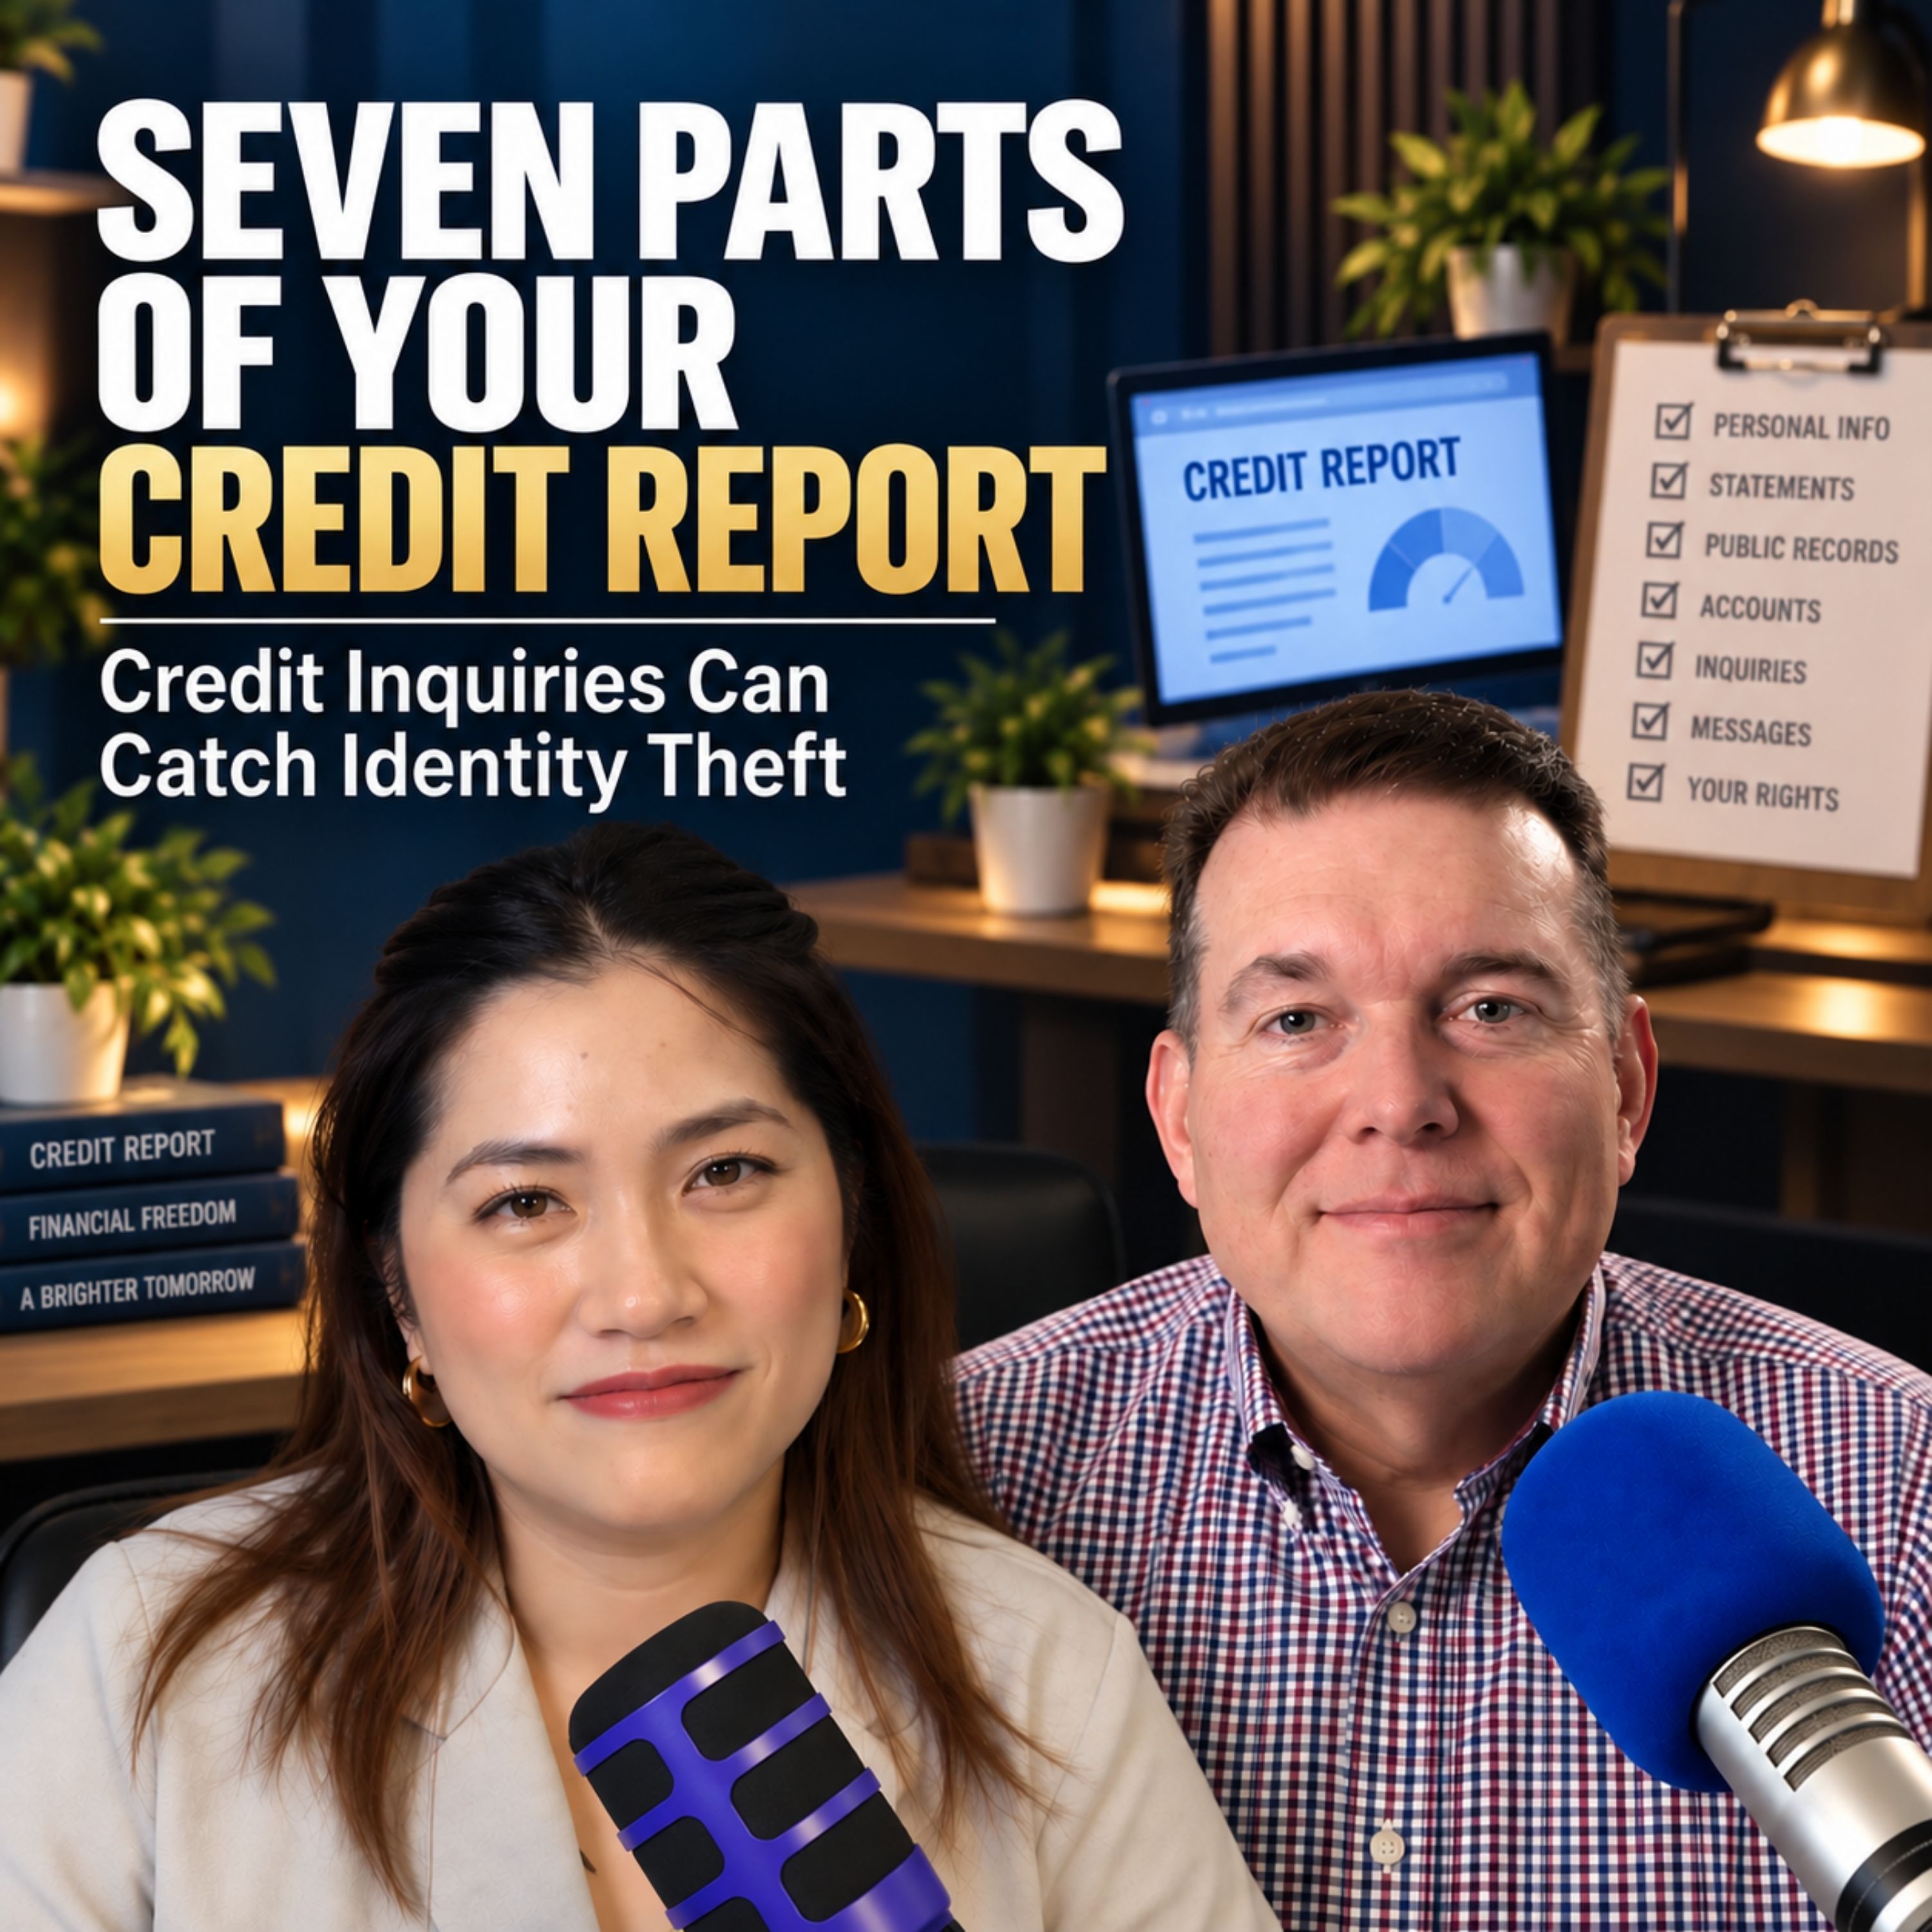
Most people have never opened their full credit report, let alone read every section of it. My cohost Juliet and I went through ours together on the show, line by line, and there are seven parts most people skip past without realizing what's actually in them.
Reading your credit report like you actually mean it
Your personal information section includes any aliases you've used, which is worth checking closely for names that aren't yours. Then there's a section for personal statements, where you can add context like a fraud narrative if something's wrong. Potentially negative items and public records come next, followed by your accounts, or trade lines, which make up the bulk of the report and show every account you've ever had, open or closed, along with your payment history.
Credit inquiries are one of the fastest ways to catch identity theft, since they show exactly who's pulled your credit and when. Round it out with messages from the bureau and a summary of your rights under the Fair Credit Reporting Act, and you've got the full picture.
If something on there looks wrong, most bureaus let you dispute it online. The creditor then has 30 to 45 days to respond, or the item comes off your report entirely. Most negative items fall off after 7 to 10 years on their own, and medical collections under $500 or under 12 months old don't get reported at all.
One thing worth knowing: a soft pull on your credit doesn't touch your score. That's what happens when a company buys a list of people matching certain criteria for marketing. A hard pull happens when you apply for credit yourself, like at a dealership, and that one does affect your score.
I'm Ralph Estep Jr., a licensed public accountant with 30 years in the business. After the credit report breakdown, we moved into a side hustle a lot of you have asked about, and I did some digging before this episode because the math people see in the ads isn't the math that ends up in their bank account.
What Rover actually pays you
Boarding dogs on Rover sounds like the easiest money in the world. You like dogs, you're already home, why not get paid for it? That's exactly what Juliet was thinking too, until we ran the actual numbers.
2026 rate surveys put typical boarding between $40 and $75 a night. Say you charge $50. Rover takes 20 percent off the top, so you're at $40 before you've paid a dime in tax. Then, because you're an independent contractor and not a Rover employee, self-employment tax takes 15.3 percent. Add your regular federal tax on top of that, and a $50-a-night rate lands closer to $30 in your pocket.
Juliet did the math with me live and her reaction said it all: what looked like $500 for ten nights of dog watching turned into $300. And that's before supplies, mileage, or wear on your home.
There's more to check before you take your first booking. Most homeowner's and renter's insurance policies specifically exclude boarding other people's animals for money, so if the dog bites a neighbor or tears up your floors, you're likely on your own. Confirm your HOA or landlord allows it, and look into whether your city requires a home occupation permit or boarding license. None of this means Rover is a bad idea. It just means the $50-a-night version of the story isn't the whole story.
Also in this episode
We covered a car loan interest deduction worth up to $10,000 a year for anyone who financed a new car assembled in the US between 2025 and 2028, plus what happens the moment a CD matures if you miss the 10-day grace period to change your mind. We also got into the FTC's new scrutiny on personalized pricing, and whether the price on your screen might not be the price on someone else's.
If you've got a money question, send it to us at becomingfinanciallyconfident.com. And if you haven't pulled your credit report yet, grab the free guide at becomingfinanciallyconfident.com/credit before you do.
Licensed Public Accountant
Ralph V. Estep, Jr. is a Delaware-based Licensed Public Accountant (LPA), author, rancher, and media host with more than 30 years of experience in finance, taxation, and small-business leadership. As the founder of Saggio Accounting+PLUS and the creator of the Ask Ralph Media network, Ralph helps entrepreneurs, creators, and everyday families replace money confusion with clarity, confidence, and practical next steps — without shame and without hype.
Ralph's work blends deep professional expertise with a coach's mindset and a communicator's heart. He has held leadership roles across public accounting, financial institutions, law firms, and technology organizations, bringing a rare combination of traditional accounting rigor and modern systems thinking to the people he serves. A graduate of the University of Delaware and Wilmington University (MBA), he is known for turning complex money topics into simple, repeatable frameworks that help people make wiser decisions and build lasting financial stability.
He is the host of Becoming Financially Confident, a live weekday show built on a single conviction: most money stress is not a character problem but a systems problem, and shame is what keeps people from fixing it. The show grew out of Financially Confident Christian, which Ralph hosted for more than 1,200 episodes across eight seasons and earned national recognition. The new show offers the same host and the same feed, opened up to a wider audience.
Through Ask Ralph Media, Ralph hosts several other programs. Grit and Growth Business… Read More
The Form That Controls Your 401k, and It Isn't Your Will